
Year 2021 has been very kind to the believers in the equity culture who had the courage to stay invested during the impressive multi year run since 2009. In the recent past, we have experienced brutal corrections in 2018 and 2020. We experienced serious Political problems, trade wars , the most serious virus for over a century, lockdown and a serious recession. The economy changed, company leadership adjusted and the stock market reflected these new trends.
We consider ourselves fortunate having been able to endure the tremendous corrections of the stock market and having focussed on technology. In recent months sector rotation has been brutal and the market very difficult to follow. A well diversified approach certainly helped the portfolios in this unpredictable environment.
A static view of valuation
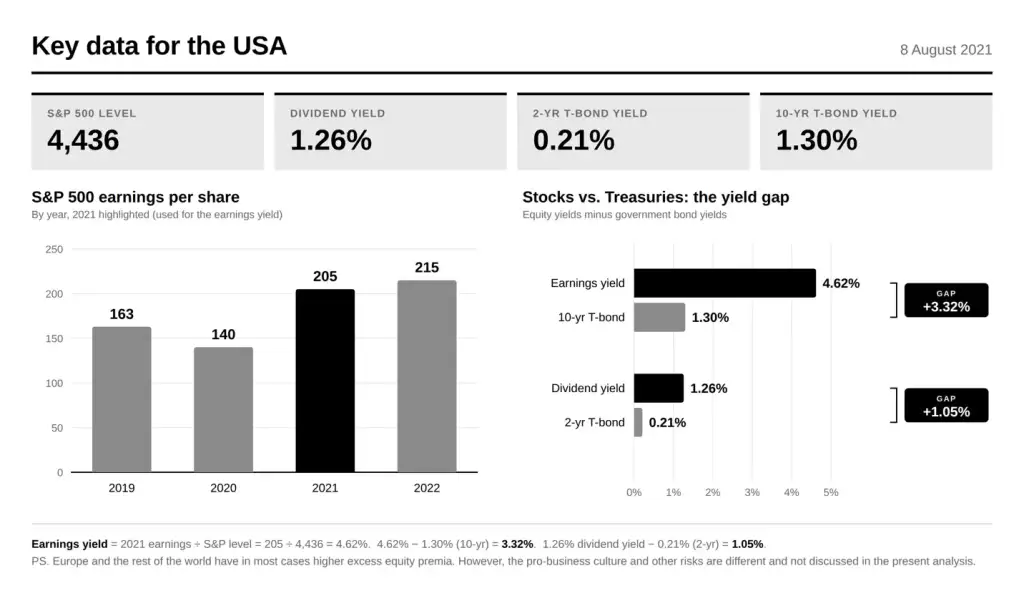
It is time to reflect again on our pro equity strategy as well as on possible tactical adjustments. From a static point of view our thesis remains that the equity risk premium exceeds considerably nominal and real interest rates. Even dividend yields are higher that 2 year rates. In our view, this environment favors stocks.
Alternative pessimistic views point to the more than sixfold appreciation since the lows of the Great Recession, to the record CAPE valuation and/or to the high replacement value of the companies (Tobin Q ratio). In addition, they maintain that accommodative Monetary and Fiscal policies and record low interest rates cannot remain forever. Optimists counter argue that excessively depressed earnings, reflecting the 2020 recession, distort the 10 year earnings(CAPE ) and the growth of intangibles distort the Q ratio.
In short, we again decide to focus on the argument that from a static standpoint stocks appear at a record low valuation relative to fixed income. Indeed in recent history, only after the crashes of 1987 and of 2008-9 the excess equity yield over interest rates have been higher. Even if we take in consideration past earnings for ten years that include the recession period !
A dynamic view of valuation
There is no doubt that the variables of the excess equity risk premium, which is our preferred valuation criterion, can change abruptly and indeed move in the negative direction.
-So far, we have followed a line of thought on inflation that eventually became prevalent after the initial scare. We considered the surge of inflationary data as temporary. This argument could be proven wrong if inflation persists. As a result, nominal Interest rates might re adjust upwards.
-In addition, earnings might suffer if the delta Covid variant becomes uncontrollable or some other shock derails the recovery scenario.
-Finally, Monetary policy might shock with abrupt and excessive tapering and/or Fiscal policy might end up with a substantially lower than expected fiscal recovery package.
The above scenarios provide plenty of ammunition for the bears !
Let’s not also forget the possible adverse unknown unknowns that are not priced in and are always more dangerous than the known unknowns ! The devil we do not know is more dangerous!
Our views
So far, the bears have missed out. Again !
As investors, we always find reasons to stay the course, remain invested and enjoy the substantial equity over performance. Some short term adjustments to exposure are always attempted. We do not disregard the fact that without doubt a correction will eventually take place. As always, nobody knows when, by how much and for which unpredictable reasons.
We are still optimistic for the prospects of future equity returns in the USA versus fixed income. Investors can still join the party, enjoy in a conservative way and… avoid excesses.
N. Ritsonis
The views and information presented are for informational purposes only and do not constitute investment advice or a recommendation. Investment decisions should take into account each investor’s objectives, financial circumstances, risk tolerance, liquidity requirements and investment horizon.